Wealth ·
Boost Your Credit Score Fast: A 90-Day Plan Before Buying a House
Your credit score can make or break your home-buying dreams. A higher score doesn’t just improve your chances of approval — it can save you tens of thousan
Free: the Financial Independence Starter Kit, a net worth tracker and FIRE calculator that show where you stand and when work could become optional.
Your credit score can make or break your home-buying dreams. A higher score doesn’t just improve your chances of approval — it can save you tens of thousands of dollars in interest over the life of a mortgage.
This guide walks you through a step-by-step, 90-day plan to boost your score and get the best possible rate, based on my personal experience and lessons from watching two friends take very different financial paths.
Why Your Credit Score Matters More Than You Think
Imagine two friends, Alex and Ben, both buying similar homes with a $600,000 mortgage.
-
Alex has a 760 credit score and qualifies for a 6.5% interest rate.
-
Ben has a 660 credit score and gets a 7.5% interest rate.
At first glance, that 1% difference doesn’t sound huge.
But over 30 years, Ben will pay $148,000 more in interest — simply because he didn’t manage his credit as well.
Alex ends up paying off his home years earlier, while Ben struggles with higher monthly payments and less money left over to save or invest.
That’s the cost of neglecting your credit.
As Warren Buffett says:
“Someone is sitting in the shade today because someone planted a tree a long time ago.”
Your financial tree starts with your credit score. And if you have 90 days before applying for a mortgage, you still have time to make meaningful improvements — if you take action now.
My Journey: From $3,000 Collateral to Financial Freedom
When I first moved to the U.S., I didn’t have a credit history. To get started, I opened a secured credit card with a $3,000 deposit. That card became my training ground.
Every month, I used it for small purchases and paid it off in full. It wasn’t glamorous, but it was the foundation I needed.
I kept that card for years, until I qualified for two regular credit cards without collateral. The discipline I built during those early days helped me achieve an excellent credit score — which later saved me thousands when it came time to finance major purchases like a car and, eventually, a home.
Looking back, that first $3,000 felt like a sacrifice. Today, it feels like the best investment I ever made.
The 90-Day Game Plan to Boost Your Credit Score
This plan is designed for maximum impact in minimum time. Each phase builds on the last, so by the time you hit Day 90, your credit score will be in its best possible shape.
Phase 1: Assess and Fix (Days 1–30)
Your goal here is to know where you stand and address major issues.
1. Pull Your Credit Reports
You can get free copies of your credit reports from all three bureaus (Experian, Equifax, and TransUnion) at AnnualCreditReport.com.
Check for:
-
Incorrect late payments
-
Accounts that aren’t yours
-
Outdated negative marks
-
Debt balances that are wrong
***Pro Tip:***1 in 5 people have at least one error on their credit report, according to the FTC.
2. Dispute Errors Immediately
If you find mistakes, dispute them online through each credit bureau’s portal:
-
Experian: experian.com/disputes
-
TransUnion: transunion.com/credit-disputes
Correcting just one late payment error can raise your score by 30–80 points.
3. Calculate Your Credit Utilization
Credit utilization is 30% of your score, and it’s one of the fastest things to improve.
-
Ideal utilization: Below 30% of your total credit limit
-
Best-case scenario: Below 10%
Example: If your total credit limit is $10,000, aim to keep balances under $3,000 — preferably under $1,000.
Quick Win:Paying down balances can raise your score within30 days*.*
Phase 2: Optimize and Build (Days 31–60)
Now that you’ve addressed errors and reduced utilization, it’s time to strengthen your profile.
4. Become an Authorized User
Ask a trusted family member with excellent credit to add you as an authorized user.
Why it works:
-
Their positive payment history appears on your report.
-
You benefit from their good credit habits.
Important:Make sure the account hasno late payments*, low utilization, and at least5+ years of history.*
5. Negotiate and Settle Collections
If you have accounts in collections:
-
Call the collection agency.
-
Offer to pay in full if they agree to remove it from your report (pay-for-delete).
If they refuse, even a paid collection looks better than unpaid.
6. Open a Secured Credit Card (If Needed)
If your file is very thin, consider opening a secured credit card — like I did.
How it works:
-
You put down a deposit (e.g., $2,000).
-
That deposit becomes your credit limit.
-
Use it for small purchases and pay in full each month.
This builds positive history fast — and gives you more control over your score.
Phase 3: Maximize and Monitor (Days 61–90)
The final stretch is about squeezing out every last point.
7. Time Your Payments Strategically
Most people pay their cards on the due date. Instead:
- Pay twice a month → once before the statement closes, once before the due date.
This keeps reported balances artificially low, boosting utilization.
8. Avoid Applying for New Credit
Each new application creates a hard inquiry, which can temporarily lower your score by 5–10 points.
Pause all new applications until after your mortgage closes.
9. Monitor Your Credit Weekly
Use free tools like:
-
Credit Karma
-
Experian app
-
Your bank’s free credit tracker
You’ll catch mistakes early and stay motivated as you see progress.
The Timeline in Action
Here’s what improvement could look like in 90 days:
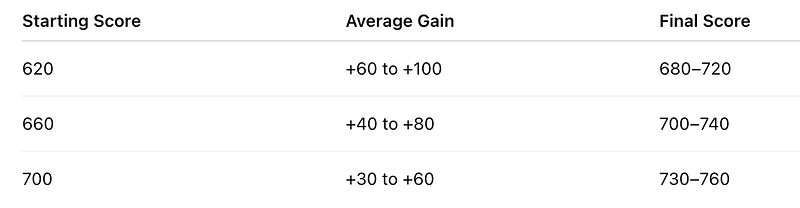
A 40–100 point increase is realistic if you follow these steps consistently.
Alex vs. Ben: The Long-Term Difference
Fast forward five years.
-
Alex, with excellent credit, refinances his mortgage at a lower rate and invests his monthly savings into an index fund.
-
Ben, with average credit, stays stuck with a higher rate and misses out on both the savings and the growth of investments.
By year five:
-
Alex has saved $14,400 in lower interest payments and has $8,000 growing in investments.
-
Ben? He’s paid more in interest and has nothing extra saved.
Good credit isn’t just about loans. It’s aboutfreeing up cash to build wealth elsewhere**.
Why This Matters: The Big Picture
Every 20-point increase can mean:
-
Lower interest rates
-
Lower monthly payments
-
Better loan approval odds
On a $600,000 mortgage:
-
A 0.5% lower interest rate saves about $180/month
-
Over 30 years, that’s $64,800 saved
That’s a college fund, a second home down payment, or a fully paid-off car — just from improving your credit.
Final Thoughts: Your Future Self Will Thank You
Improving your credit isn’t about perfection. It’s about progress and consistency.
By following this 90-day plan, you’ll position yourself to buy your dream home — and own it on the best possible terms.
“The best time to plant a tree was 20 years ago. The second-best time is now.”— Chinese Proverb
Start planting your financial seeds today. Your future self will be grateful you did.
Your Turn: Share Your Journey
What steps have you taken to boost your credit score? Have you ever seen a big score jump before a major purchase?
Drop a comment below — your story could help someone else achieve their dream of homeownership.
Let’s grow this community by learning from each other.
Towards Finance
Thank you for being part of the TF community.
-
📚 View more content in the Towards Finance publication.
-
📈 Join thousands of investors and entrepreneurs to maximize your success by subscribing to our newsletter.
-
🤝🏽 Follow us on X and LinkedIn for more finance and data science content.